
Multiple Central Bank Digital Currency Bridge (mBridge): New Cross-Border Payment Infrastructure Amidst Geopolitical Shifts


I. What is mBridge?
The Multiple Central Bank Digital Currency Bridge (mBridge) is a cross-border payment and settlement platform built on Distributed Ledger Technology (DLT). It aims to enable central banks and commercial banks of participating countries to conduct peer-to-peer cross-border transactions and synchronized foreign exchange settlements using their respective Central Bank Digital Currencies (CBDCs).
The project originated in 2019 as a bilateral pilot between the Bank of Thailand and the Hong Kong Monetary Authority (HKMA). In 2021, it was officially upgraded to a multilateral project, jointly initiated by the Digital Currency Institute of the People's Bank of China (PBOC), the HKMA, the Bank of Thailand, the Central Bank of the UAE, and the Bank for International Settlements (BIS) Innovation Hub. In 2022, the project completed its first real-value transaction pilot. By mid-2024, it reached the Minimum Viable Product (MVP) stage, after which the BIS handed over the project to the participating central banks for autonomous operation in October 2024.
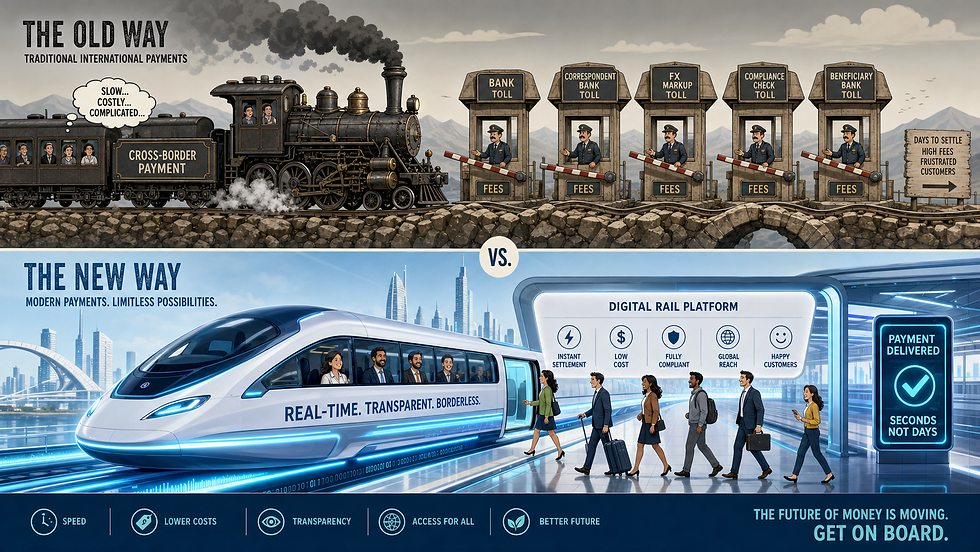
From a technical architecture perspective, the core of mBridge is a dedicated blockchain called the "mBridge Ledger." There is no centralized system; each participant independently operates its blockchain node, manages its database, and safeguards its keys. Central bank nodes are directly connected to achieve interoperability among commercial banks. The platform supports atomic transactions and synchronized foreign exchange settlements, theoretically compressing traditional cross-border payments from 3 to 5 business days to mere seconds.
II. Key Events: The Exit of Saudi Arabia and the Departure of the BIS
Saudi Arabia's "Quiet Exit"
In September 2026, the UK's Financial Times revealed that the Saudi Central Bank (SAMA) had exited mBridge after completing a proof-of-concept on May 13, 2025, and is no longer an active participant. The Saudi Central Bank stated that it joined as an observer in 2023 and entered the proof-of-concept stage as a formal participant in 2024; its exit was a normal step according to the original plan.
Saudi Arabia's exit garnered widespread attention due to its geopolitical symbolic significance. As a long-term US ally in the Middle East and the world's largest oil exporter, Saudi Arabia's participation was previously viewed by the outside world as a key signal of mBridge achieving a breakthrough in the oil trade settlement scenario. Saudi Arabia's departure makes it difficult for mBridge to replicate "oil settlement"—its most imaginative application scenario—in the short term.
However, multiple informed sources emphasized that given Saudi Arabia's involvement was quite limited from the start, "extrapolating" its exit as the result of US pressure is inaccurate. Other sources indicate that while the Saudi Central Bank is no longer participating publicly, it remains in contact with the project in a more low-key manner.
The Departure of the Bank for International Settlements
Saudi Arabia's exit is not the first "departure" mBridge has encountered. The BIS exited the project in October 2024, at which time the Financial Times reported that Washington had exerted pressure on the BIS. Then-BIS General Manager Agustín Carstens responded that the institution had "graduated" from the project and handed leadership over to the central bank partners, stating it was "not because of failure, nor out of political considerations." When the BIS exited, mBridge already had over 30 observer institutions, including the central banks of the Philippines, Indonesia, South Korea, the European Central Bank, and the Federal Reserve Bank of New York's Innovation Center, indicating extensive project coverage.
III. Core Analysis: The Tension and Misconceptions of the "De-Dollarization" Narrative
(I) mBridge is Technical Infrastructure, Not a "De-Dollarization" Alliance
In public discourse, mBridge is often directly equated with "de-dollarization," but this oversimplification obscures its true positioning. mBridge is primarily a payment technology and settlement network; its function is to allow participants to bypass the traditional correspondent banking system and achieve more direct cross-border settlements. Participants can perfectly well continue using the US dollar system while utilizing mBridge as an alternative payment channel.
In other words, mBridge challenges the "plumbing" of the correspondent banking system, not the status of the US dollar as a reserve currency and unit of account. What is truly being bypassed is the inefficient architecture of multiple layers of correspondent banks in cross-border payment settlements, not the core role of the US dollar in international trade and finance.
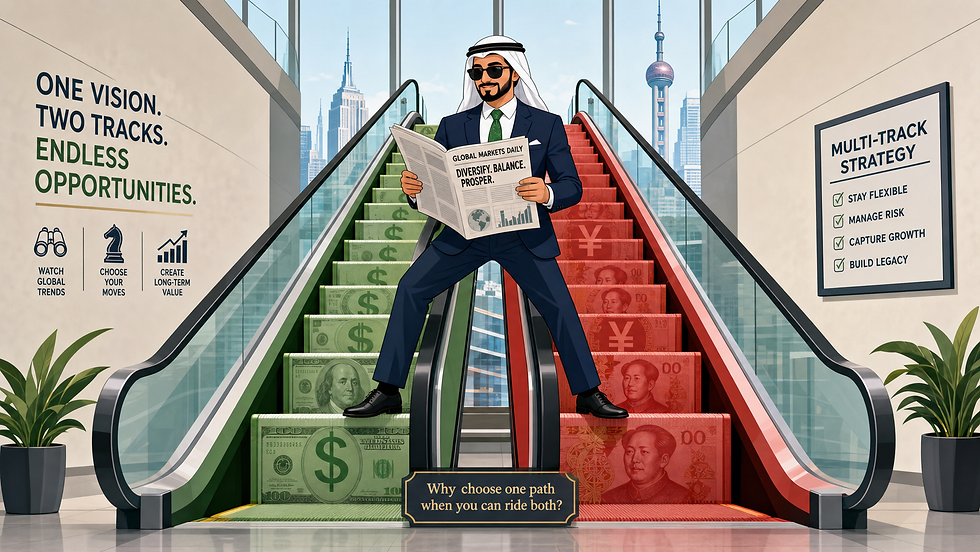
(II) Saudi Arabia's Multi-Track Financial Strategy: Not Taking Sides, But Adding Options
The key to understanding Saudi Arabia's exit from mBridge lies in recognizing that the Saudi Riyal has been pegged to the US dollar at a fixed rate of 3.75 Riyals to 1 USD since 1986, and the dollar remains the absolute foundation of Saudi Arabia's monetary system. Saudi Arabia's joining of mBridge was from the outset a limited technical study, not a strategic declaration of "breaking away from the dollar." Correspondingly, its exit should not be interpreted as "re-embracing the dollar."
At the same time, Saudi Arabia is indeed actively building alternative channels outside the US dollar system. In November 2023, the Saudi Central Bank and the PBOC signed a bilateral local currency swap agreement worth up to 50 billion RMB, which remains in effect. This means Saudi Arabia is not "choosing one or the other" between the US dollar and the RMB, but rather simultaneously holding multiple channels to reduce reliance on any single payment system.
This strategy is corroborated on a broader level. China continues to advance local currency settlement cooperation with BRICS nations such as Brazil, Russia, and South Africa, and the use of the RMB in energy trade has seen significant growth following the Iran war. Saudi Arabia's choice is not an isolated case; it reflects a common trend among emerging market countries seeking "incremental options" outside the US dollar system.

(III) The Dominance of the RMB in mBridge and Its Implications
Although mBridge is positioned as a multi-currency platform, the digital RMB holds absolute dominance in actual transactions. By the end of 2025, mBridge had processed a cumulative total of 4,868 cross-border payment transactions, with a transaction value equivalent to approximately 477.8 billion RMB, of which the digital RMB accounted for about 96% of the transaction volume across all currencies. This data reveals a structural characteristic of mBridge: it has essentially become the core channel for the cross-border application of the digital RMB, while the usage scale of other participating currencies is far from sufficient to form a true "multipolar" landscape.
This is both a hallmark of the project's success and the root of the external pressure it faces. The core concern of US policymakers is not mBridge's current actual transaction volume, but its potential to evolve into an alternative settlement infrastructure capable of bypassing US dollar clearing and financial sanctions. The 2024 annual report of the US-China Economic and Security Review Commission (USCC) explicitly pointed out that mBridge could provide a new channel for countries seeking to evade US sanctions. The Trump administration has even threatened to impose 100% tariffs on BRICS countries promoting alternatives to the US dollar.
IV. Current Project Progress and Prospects
Despite the exit of Saudi Arabia and the departure of the BIS, mBridge has not stopped expanding. The Monetary Authority of Macao joined the platform in 2026 and officially launched in June; the first batch of 11 Macao banks completed integration, executing 23 cross-border transactions on the first day. The Bank of Mongolia joined the steering committee in June 2026, becoming a formal member with the same rights and obligations as the founding members. Furthermore, over 30 central banks and international organizations continue to participate in the project as observers.
On the commercialization front, the platform has entered a stage of deep preparation. It is expected to be operated by an institution headquartered in Hong Kong, with costs estimated to be about half of traditional international payment systems. Gene Ma, Head of China Research at the Institute of International Finance (IIF), pointed out that the global payment landscape is shifting from single SWIFT dominance to multi-network competition, and mBridge will become one of them.
Looking at data growth, mBridge's cumulative transaction value increased by approximately 2,500 times from early 2022 to early 2026, reaching over 55 billion USD. This growth rate indicates that despite persistent geopolitical headwinds, the actual demand for the platform's use continues to grow.
V. Conclusion
mBridge represents a genuinely technically original and institutionally experimental attempt in the field of cross-border payment infrastructure. Its value lies not in whether it can "replace SWIFT" or "dismantle dollar hegemony" in the short term, but in validating a possibility: central banks from different jurisdictions can conduct direct, real-time, low-cost cross-border settlements using their respective digital currencies on a shared distributed ledger, without needing to route through multiple layers of correspondent banks.
The exit of Saudi Arabia and the departure of the BIS undoubtedly add uncertainty to the project, but simply characterizing this as a "setback for de-dollarization" is inaccurate. Saudi Arabia's multi-track strategy, the absolute dominance of the digital RMB on the platform, and the project's expansion to new members in places like Macao and Mongolia collectively form a much more complex picture. A more accurate assessment might be: mBridge is proving its feasibility as technical infrastructure, but whether it can become a systemically important "parallel channel" in the global payment system still depends on the race between geopolitical maneuvering and the pace at which commercial application scenarios are expanded.
[Limited-Time Expert Consultation Invitation]
FOFA sincerely invites visionary entrepreneurs and investors to engage in deep, practical exchanges regarding the aforementioned trends, we will provide you with a complimentary expert planning consultation to help you tailor a specific entrepreneurial path or investment blueprint, allowing technology leverage to serve your asset appreciation.
Book your strategic dialogue NOW:


Comments